
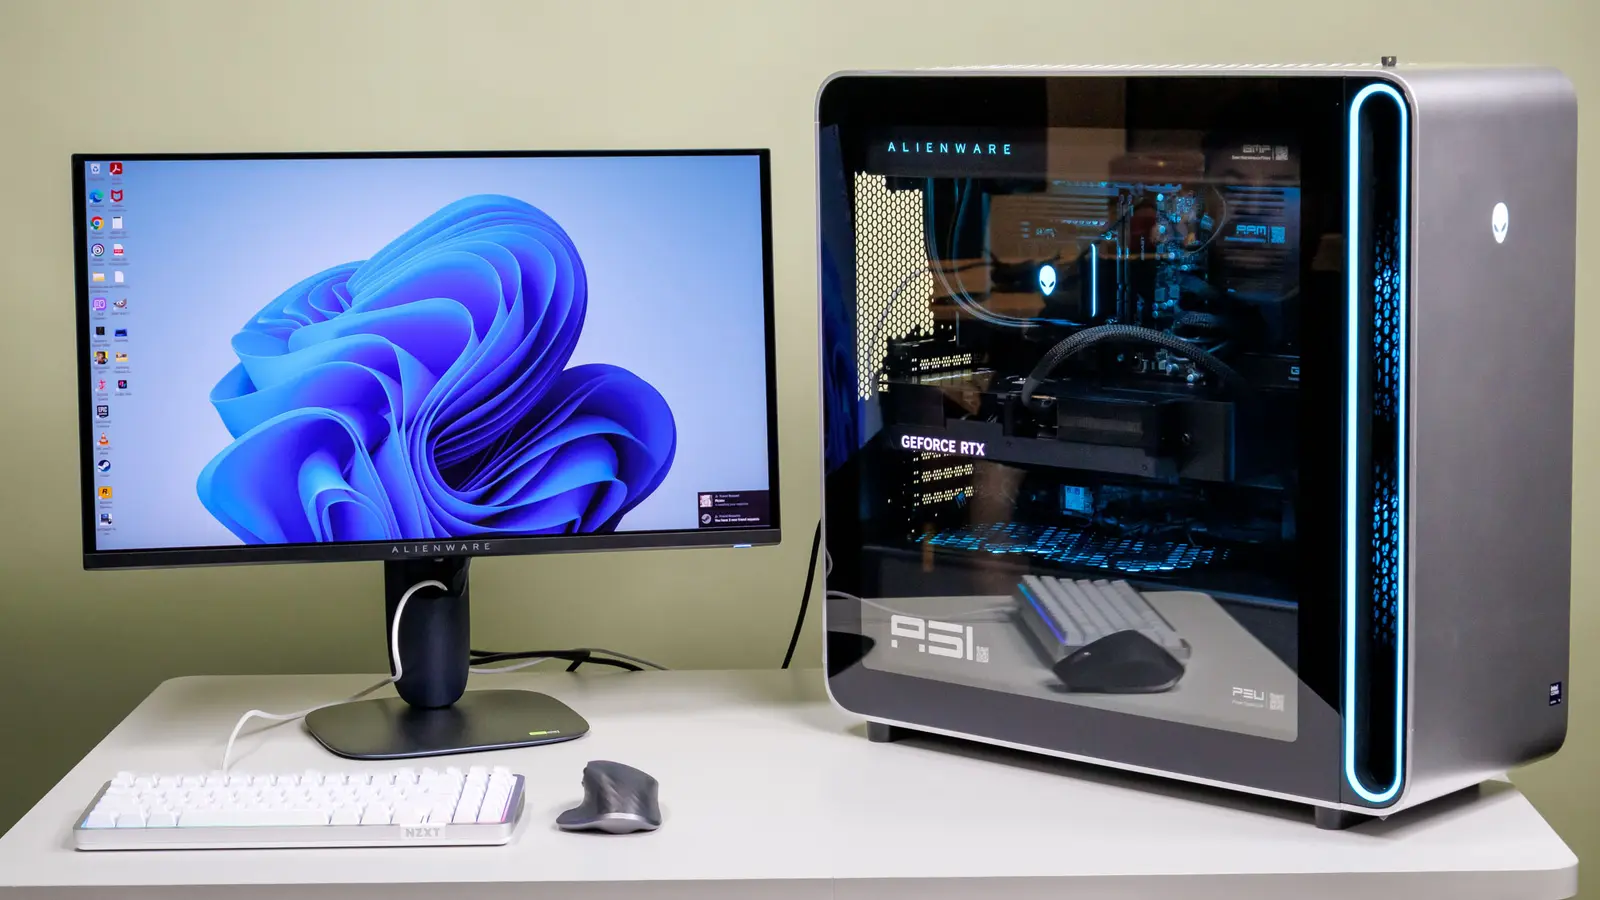
The hum of new datacenter racks turned into an unexpected headache for anyone selling laptops. Shipments of personal computers fell 4 percent in the second quarter of 2026, slipping to roughly 65 million units and interrupting the recovery that had run since early 2025.
What changed so fast? A spike in DRAM and NAND prices, triggered by a rush to equip artificial intelligence data centers, pushed component costs sharply higher. Makers faced a stark choice: absorb those costs or pass them on to buyers. Most chose the latter, and demand cooled as a result.
When components dictate strategy
IDC’s forecast now points to an 11.3 percent decline in PC shipments for the full year, with a steeper fall—around 20 percent—expected in the fourth quarter. Those numbers are a reminder that hardware markets are still tethered to supply-side shocks. Short-term demand can be fragile when a few key parts spike in price.
Apple bucked the overall trend, reporting a 13 percent rise in MacBook shipments, largely driven by strong uptake of the lower-cost MacBook Neo. On the Windows side, ASUS managed modest growth at about 4 percent, while heavyweights such as Dell, Lenovo, and HP saw declines of up to 9 percent.

There is a clear consequence: consumers hunting for budget systems are getting squeezed. Higher component costs make affordable notebooks harder to produce without eroding margins. So vendors are nudging the market toward pricier models, many of which include AI-ready features that at least give a tangible reason for the premium.
Who benefits from that shift? Manufacturers and component suppliers, if they can sell fewer units at higher prices. Buyers with tight budgets lose. The market may consolidate around premium designs equipped for AI workloads, where margins justify higher retail tags and component investments.
This supply-driven pricing squeeze stopped the PC market’s momentum—and it may reshape the industry toward higher-priced, AI-capable machines.
Look ahead and watch two variables. One: how quickly DRAM and NAND supply expands to relieve pricing pressure. Two: whether chipmakers and cloud builders slow their aggressive datacenter rollouts. If prices ease, affordable PCs could rebound; if they do not, expect product roadmaps and marketing to lean even harder into AI features that justify a costlier purchase.
For now, the Q2 numbers are a reminder that hardware recoveries can be fragile when a single cost center—memory and storage—decides the pace of everything else.
“I love exploring gadgets, apps, and trends that redefine how we connect, work, and play in a digital world.”

Discussion
Leave a Comment
Comments
No comments yet. Be the first.